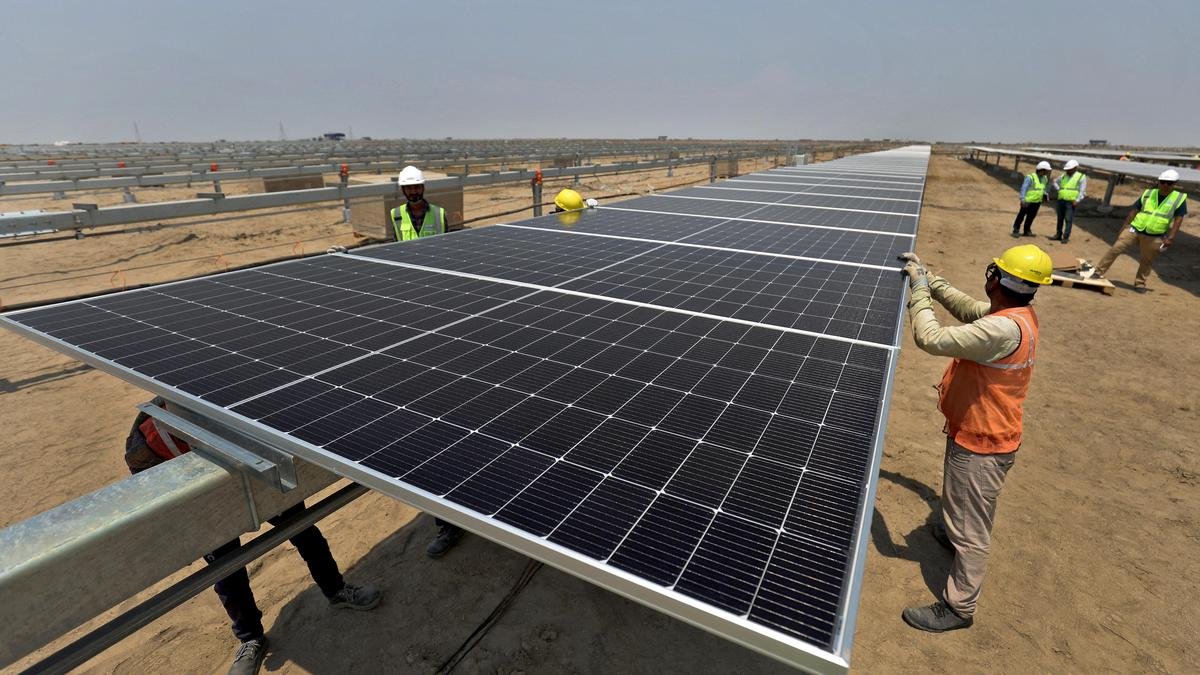
GEC III: Bridging the geographical and temporal disparity
India’s renewable energy sector is now entering a crucial phase of completing the circuit with the integration of states through a robust national grid, even as multiple challenges test ambition.
The Union Cabinet has given its nod to the ₹1.86 crore Green Energy Corridor (GEC-III) Phase III, which is designed to close the geographical and time gap.
Nearly three-fourths or ₹1.36 crore for national transmission systems and ₹50,000 crore for 50 GWh BESS or Battery Energy Storage System (BESS) have been earmarked for GEC-III, the main objective of which is to improve the evacuation of renewable energy from production-rich states and efficiently shift it to the Centre.
This means a tectonic shift from generation to reliability.
With a total central financial support of ₹54,082 crore, the project also has a non-viability financing mechanism to help attract private capital and enable large-scale deployment of storage, making GEC-III more financially sustainable and commercially attractive.
The need to boost renewable energy infrastructure comes from the International Energy Agency’s (IEA) view that India’s electricity demand is expected to grow by an average of 6.4% per annum until 2030.
India has commissioned 263 GW of renewable capacity by January 2026, while the national policy is to reach 500 GW by 2030. Plans to integrate more than 500 GW by 2030 and more than 600 GW by 2032 have gained momentum.
Central Electricity Authority (CEA) data shows that renewables contributed 17% to electricity generation in FY 2025-26 compared to 14% in the previous fiscal, while reports suggest that renewables account for more than 50% of India’s installed power capacity.
GEC-III is the answer to the gaping gap between the installed capacity of renewable sources and the actual production of electricity.
From generation to integration
Through GEC-III – designed to evacuate up to 135 GW of renewable energy and scheduled for completion by FY2032-33 – a greater share of renewable electricity is expected to reach the grid as generation does not necessarily occur at the point of consumption.
Solar and wind projects are largely in resource-rich areas—Rajasthan and Gujarat for solar/wind, parts of southern India for wind and solar, and the Himalayan region for hydro—while demand for electricity is across industrial and urban centers.
Without adequate national and interstate networks, additional generation can lead to congestion and constraints, and GEC-III is an attempt to build a physical architecture towards this.
Storage changes the equation
The 50 GWh battery storage that sets Phase III apart from previous phases seeks to address nuisance interruptions, congestion, peak curtailment and off-peak demand in the renewable energy sector.
In addition, increased deployment of BESS may create demand for battery manufacturing, engineering, procurement and construction services, grid management technologies, and ancillary services.
It has the potential to improve the economics of other forms of storage such as pumped storage. The government has already introduced non-viability funding to support battery storage, creating a wider policy framework for increasing storage capacity.
Structural architecture
The architecture is woven around a central state – grid operator, with the Ministry of New and Renewable Energy (MNRE) responsible for the policy framework and central financial assistance for GECs.
CEA doubles the role of planning and technical assessment while ensuring that the state’s needs fit into the broader goals of the national plan.
To ensure smooth functioning, central and state transmission services have been entrusted with key roles in planning and execution of interstate and national transmissions.
With an eye on inclusive development, Grid-India and regional dispatchers oversee the operation of the cost, planning and management of renewables variability, making the entire system inclusive.
Regional Energy Management Centers have also been established to improve renewable forecasting and grid management.
Previous phase
Approved in 2015, GEC-I focused around eight renewable-rich states to build about 9,767 circuit km (ckm) of transmission lines and 22,689 MVA of substations, enabling 24 GW of renewable energy.
According to the annual report of the Ministry of Energy for the period 2025–26, 9,170 ckm were built and 22,116 MVA substations were commissioned. Six states have completed their projects, while Gujarat and Maharashtra have received extensions till March 2026.
Approved in 2022, GEC-II included seven states, with a revised target of 7,919 ckm and 22,448 MVA, supporting 20 GW of renewable energy.
Implementation was considered somewhat sloppy as only 1,124 ckm of transmission lines and 6,860 MVA substations were commissioned as of June 2026, although 93 out of 95 packages were tendered and 85 awarded.
Combined, the first two phases saw a success rate of 59% as they integrated 26 GW of renewable capacity against the planned 44 GW. GEC-I and II were mainly transfer programs.
The success rate shows that the corridor concept is working, but also highlights the larger scale of Phase III requiring faster execution. After identifying system gaps, it combines transmission, storage and network flexibility to close the geographic and time mismatch.
Key concerns
High capital intensity would mean that funding, procurement and cost recovery remain critical issues. Scale increases the complexity of coordination because a delay in one part of the generation-transmission-storage chain can have a ripple effect on other segments.
Taking into account that the implementing agencies are state transmission companies, differences in land acquisition, right-of-way (identified as a major source of delay in previous phases), approvals and implementation capacity may lead to uneven progress.
Given the rapid pace of technological change, the economics of storage will determine whether or not 50 GWh becomes an economically efficient asset.
Transmission lines require physical corridors across multiple jurisdictions, so delays can leave completed production facilities waiting for evacuation infrastructure.
Marking the risks of consumer tariffs, although the central aid is supposed to include transmission charges, the total cost of building and operating the network must ultimately be covered by the electricity system.
Global experience
The network problem is global. The IEA estimates that variable renewables will account for 27% of global electricity generation by 2030, while more than 2,500 GW of renewable, storage and high-load projects are currently idled in grid queues worldwide.
China, which has reportedly built the world’s most extensive renewable energy transmission architecture, is expected to account for around 60% of global renewable capacity expansion by 2030.
As part of the 2016 North Seas Energy Cooperation initiative, voluntary regional energy initiatives, nine European countries and the European Commission took steps to build an integrated offshore grid and set a target of at least 300 GW of offshore wind power by 2050, with a target of 120 GW by 2030. The European Commission estimates investments in electricity networks this decade at €584 billion.
Within Europe, the NordLink connection between Germany and Norway allows excess German wind energy to flow to Norway, while Oslo’s water reservoirs provide Germany with renewable generation.
Australia has already identified and is in the process of scouting for potential REZs or Renewable Energy Zones and has explicitly linked their development to transmission, long-term storage and grid reliability.
The US is also undertaking major transmission modernization programs.
Greater importance of GEC-III
The country is attempting to expand its physical infrastructure for renewable electricity as it increases renewable energy production.
The goal is to expand the transmission network from approximately 5.04,040,000 ckm in February 2026 to 6.48,000,000 ckm by 2032.
GEC III will determine how effectively India converts its vast renewable energy potential into reliable electricity.
A larger pool of predictable low-carbon energy is essential for the decarbonisation targets of large users such as manufacturing and data centres; here it comes as a GEC-III solution.
As a secondary byproduct, better transmission and storage could improve the availability of clean energy for electric vehicles, green hydrogen and other energy-intensive industries.