₹3 cr house, ₹80 lakh in mutual funds: Why India’s rich are still trapped in high-stress jobs despite their wealth | Today’s news
AND ₹3 million homes, ₹80 million in mutual funds and ₹35 million fixed deposits seem to offer financial security. However, the viral post on X sparked a debate about why people with significant assets may still feel unable to leave high-stress jobs because of ongoing financial obligations.
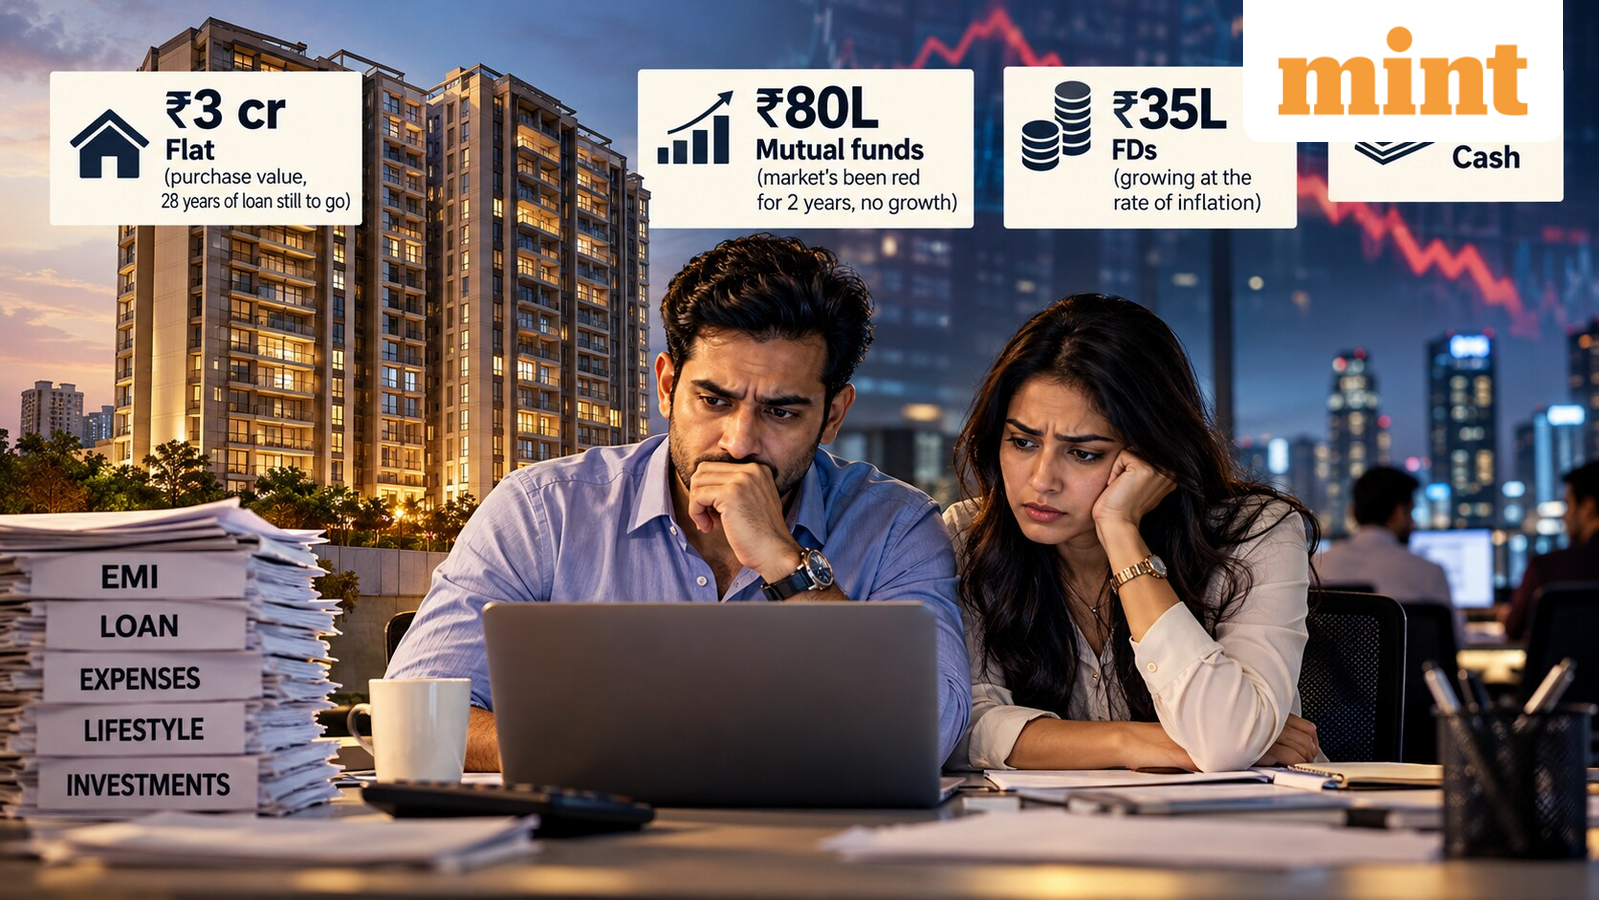
A post shared by @Theonenameddamn describes a married couple in their 30s from Delhi whose assets include a house bought for ₹3 crore with 28 years of loan, investment and cash repayments remaining.
“Speaking to a couple in their 30s from Delhi. They have:
₹3 kr: Apartment (purchase value, 28 years of loan still left)
₹80L: Mutual funds (the market has been in the red for 2 years, no growth)
₹35L: FD (growing at the rate of inflation)
The account argued that despite their wealth, the couple could not afford to leave their demanding jobs.
“They’re rich on paper. And yet they can’t afford to leave their high-stress jobs. Living well in the flat, but the EMIs never stop.”
Every asset he owns either grows by 7-10% or doesn’t grow at all. There are millions of Indians in this silent trap.”
₹3 Million Homes, 28 Years EMI: Cost of Home Ownership
The post attracted comments questioning whether buying an expensive house at an early age can limit wealth creation.
Read also | Challenges faced by women investors in managing family assets; how to address them
One user wrote, “3 Crore house is too big when they are too young. Better to stay on rent and build corpus and then buy a good house in city 2 after retirement.”
EMIs create reverse compounding and kill wealth creation potential.”
Another commented, “A 3 CR flat in Delhi/Gurgaon is not worth it.”
A home can provide housing security and appreciate in value, but a self-occupied property does not necessarily generate income. Large EMIs can also reduce the money available for investments and day-to-day expenses.
‘This is not a trap’: Users discuss financial options
Another user argued that social pressure rather than a financial trap could explain such decisions.
“Make no mistake, this is NOT A TRAP, Pple submit to this fully and willingly, it’s sheer pressure of the socially acceptable where people brag about their EMIs to each other, THIS IS NOT A TRAP.”
A fourth user questioned the release of personal financial information, writing: “Who are these people who just give their financial details in such detail?”
₹35 lakh in FD: Why investors resist fixed deposits
In defense of Fixed Deposits, another user wrote, “I don’t know why people have a habit of mocking FD
FDs are a fantastic vehicle to invest in if you have low interest and want to remain liquid. You will also see the compounding effects in a few years.”
Fixed deposits offer predictable returns, while the performance of mutual funds depends on market conditions and the underlying investments. Earnings after inflation and taxes may vary from total rates.
Read also | Chinese Bride Gifts ASUS ROG Astral RTX 5090 GPU; the groom is crying | Viral video
The outstanding loan balance, EMIs, income and expenses of the couple are not disclosed, making it difficult to assess their true financial situation.
Their reported ₹1.23 million in mutual funds, FDs and cash does not determine whether they can quit their jobs. The discussion highlights a key distinction between personal finance: owning substantial assets is not the same as having enough liquid resources to sustain non-salary expenses.