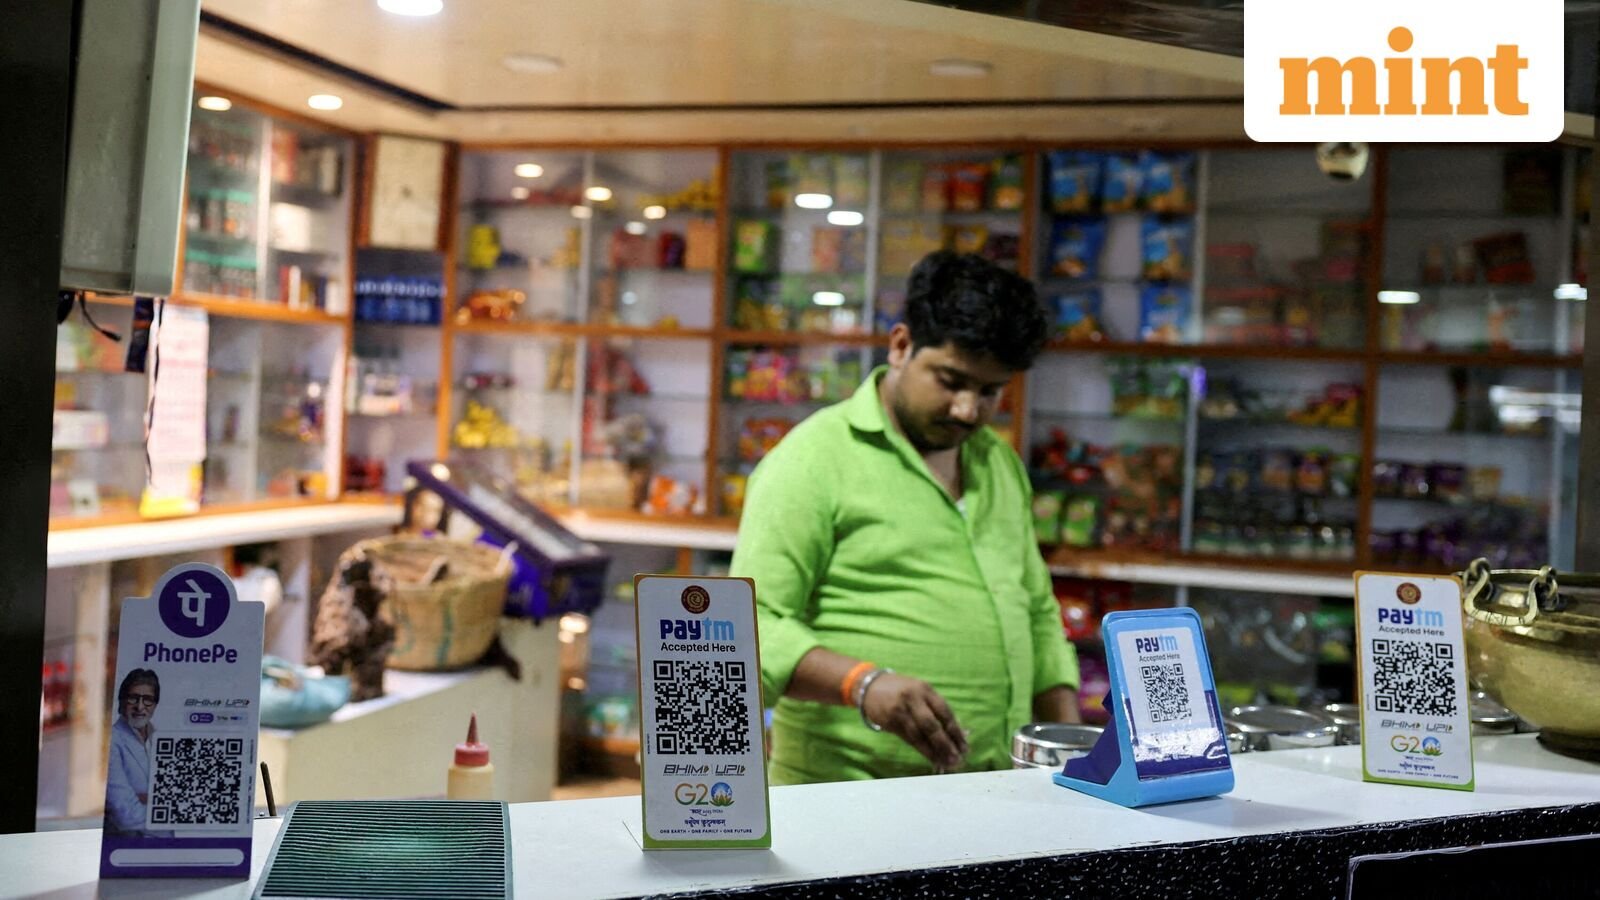
The UPI charge is set to increase costs for some merchants as the industry waits for the rollout of | Today’s news
Bengaluru: India’s move to impose merchant discount rates (MDR) on select UPI transactions will bring new costs to some businesses, even as most merchant payments remain free. New research suggests the impact will vary widely, with some merchants expecting significant monthly bills, while many expect the fees to have little impact on their margins.
A merchant survey included in How Urban India Pays 2026, a report by the Pahlé India Foundation in partnership with Amazon Pay, found that 25% of respondents expect to pay more than ₹5000 per month. Another 58% of merchants expect to pay ₹1,000 or less, including 13% who expect no fees, suggesting that costs may be falling unevenly across businesses. Over 95% of UPI payments to merchants will remain free under the new merchant discount rate.
Read also | Can the government stop merchants from passing UPI MDR charges?
Last month, National Payments Corporation of India (NPCI), which operates the Unified Payments Interface (UPI), announced a merchant discount on select merchant-to-merchant UPI transactions effective October 15, while person-to-person transactions remain free.
Quick answers to key questions
•5 QUESTIONS
MDR is a fee merchants pay to banks and payment companies for processing digital payments. The proposed standard rate is 0.4% on selected merchant-to-person UPI payments above ₹2,000, capped at ₹300 per transaction; personal payments remain free.
NPCI has delayed the rollout until immediately after Diwali. She has not yet announced the revised implementation date.
Eligible small merchants using the specified UPI QR arrangement remain exempt, including payments above ₹2,000. Exemption applies to merchants within the monthly limit for UPI receipts; they enter the category of taxpayers after exceeding it for three consecutive months.
A charge imposed specifically because a customer opts for UPI is considered a surcharge, even if it is called a convenience charge. A related article says that NPCI rules prohibit giving MDRs to customers; the actual service charge must apply consistently across payment methods.
In a survey of 1,054 merchants, 25% expected monthly fees of more than ₹5,000, while 58% expected to pay ₹1,000 or less, including 13% who expected no fees. These are estimated costs, not actual bills.
However, on Tuesday, the NPCI postponed the levy until immediately after Diwali. The adjusted implementation date will be announced separately. Diwali falls on November 8 this year.
MDR is a fee merchants pay to banks and payment companies for processing digital payments. Under UPI merchant payment above ₹2,000 will attract 0.4% recharge with maximum cap ₹300 per transaction, subject to exemptions and industry concessions.
Expected costs captured
The merchant survey captures expected costs rather than actual bills. The marketer survey in the report included 1,054 kirana owners and other marketers.
In an interview with Mint, Amazon Pay India CEO Vikas Bansal said that merchant payment services could expand beyond the basic acceptance of QR codes as the industry prepares for the rollout of MDR.
“Merchant acquisition deals will continue to be an opportunity for us… We expect merchant offerings to shift from basic payments to higher value-added services in the future,” Bansal said.
He cited card acceptance, buy-now-pay-later options, rewards and loyalty programs as ways for payment providers to deepen cooperation with offline merchants.
Read also | Walmart-owned Flipkart is considering opting for an ESOP for employees
Businesses that expect monthly MDR bills above ₹5,000 usually ensures a higher value sale, the report said. Some merchants interviewed suggested increasing the transaction limit for the z fee ₹2000 to around ₹5,000 which would keep more of their payments free. Others have proposed a slab-based structure, with fees varying according to the value of the transaction rather than one standard rate.
Nevertheless, 48% of respondents described the expected costs as insignificant or only slightly significant. The same traders expected no or only a slight impact on their margins.
About 35% reported monthly UPI income ₹1 lakh or less, the turnover band relevant for small trader exemption. Eligible small merchants accepting payments through UPI’s specified Quick Response (QR) arrangement remain exempt, including payments above ₹2000. They enter the paying category after exceeding the monthly limit for three consecutive months.
Clearer communication can help
Clearer communication about the exemption and zero MDR for payments up to ₹2,000 would help smaller traders understand their liability, the report said. Being above the monthly turnover limit does not mean that every transaction is charged.
For 44% of respondents, payments above ₹2,000 accounts for a quarter or less of their UPI transactions. As a result, most of their payments would remain free, broadly in line with NPCI transaction volume data, the report said.
UPI is already central to these businesses. More than half, or 53%, get more than half of their sales through it, including 35% who get 51-75% and 18% who get more than three-quarters. Only 3% get less than a tenth of their revenue through UPI.
Another 53% expect customers to continue paying as they are now or switch to other digital modes. However, only 43% said they would continue to accept UPI as usual.
Respondents include kirana and convenience stores (36%), services (18%), wholesale (13%), other retail stores such as electronics, fashion and pharmacies (13%), restaurants (5%), fuel retailers (5%) and other businesses (10%). Three out of four get between ₹50,000 a ₹10 crore per month through UPI.
Faster access to money
In addition to acceptance, merchants want faster access to their money. About 72.1% of merchants surveyed expressed hesitation about digital payments, citing processing delays. The report recommended pairing MDR with faster settlement and working capital credit based on UPI transaction history and business analytics.
“To grow as an ecosystem, we have to grow on both sides,” Bansal said, referring to consumers and merchants. He also pointed to other industry players developing AI-led inventory management and workflow tools for enterprises.
Read also | Under the Radar: How India’s Payday Loan Apps Survived the Crackdown
Consumer findings show a similar need to move beyond basic payments. Across five credit products, including buy-now-pay-later (BNPL) credit cards and free installments, average awareness was 88% but average take-up was 31%. Almost two-thirds of respondents have never applied for digital credit through an app. Of those who signed up, 24% dropped out midway through the process.
Bansal said consumers have grown to trust payment apps, but haven’t developed the same confidence in borrowing through them.
“The trust that digital apps have earned in payments needs to be earned in financial services as well,” he said.
In Tier 2 cities, 60% of respondents have used BNPL at least once. In Tier 1 cities, 42% of people knew about it but never used it. Among salaried respondents, 66.5% of women used BNPL or EMI compared to 59.3% of men.