In BRICS, India must use NDB
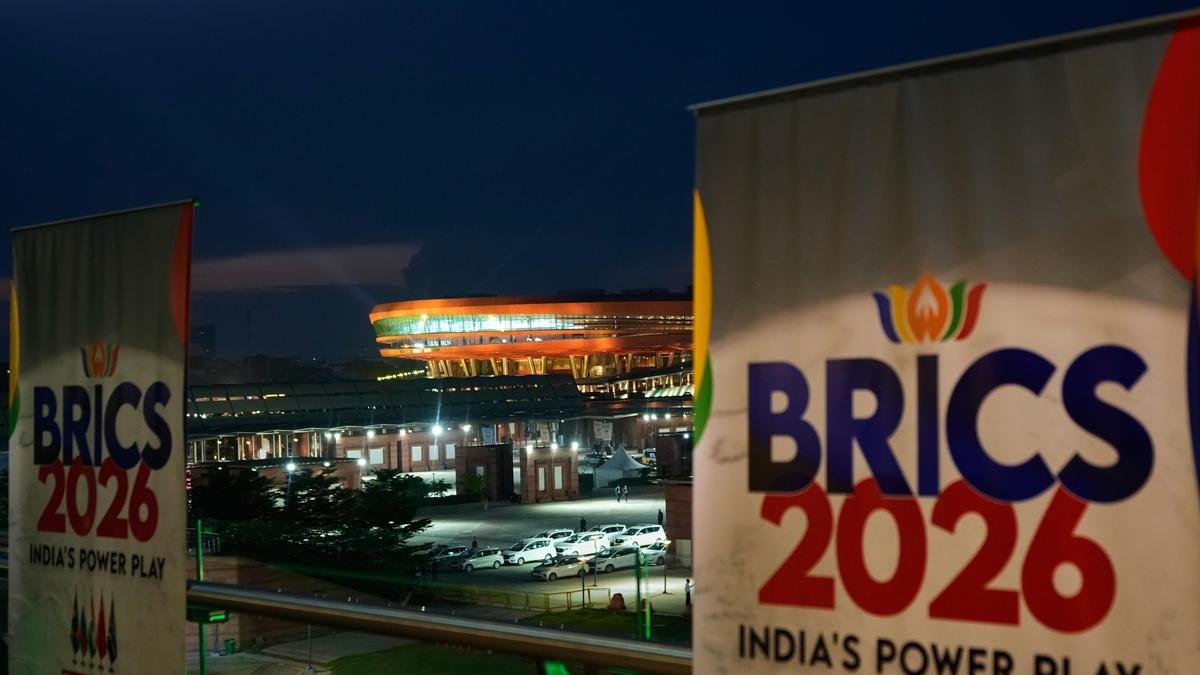
On September 12, BRICS leaders met at the Bharat Mandapam in New Delhi, with India holding the chair and therefore the pen. When the BRICS met in 2011, its five members contributed 20% of global GDP but held only 11% of voting rights in the International Monetary Fund (IMF). Today, the expanded grouping accounts for nearly 40% of global GDP and 55% of the world’s population, but the vote share has barely expanded.
Apart from this complaint, BRICS does not and will never have a coherent geopolitical identity. Russia, China and Iran would like it to be anti-Western, while India, Brazil and South Africa insist it is better understood as non-Western. Given these differences and the importance of Indo-US ties, Delhi cannot lend itself to a Beijing-Moscow de-dollarization drive. Not only would it add fuel to the fire at a time when relations with Washington are already strained, but it would also be an unsustainable proposition to defend in the medium term.
India’s approach to BRICS must be subordinated to the broader constraints and contradictions that its membership presents – maximizing the potential of the grouping without strengthening Beijing’s overall strategic position. Within these limitations, there are still options to keep groupings relevant.
To make NDB count
One of the areas where BRICS can most significantly contribute to the global financial order without overtly threatening or challenging US dominance is in expanding the effectiveness and membership of the New Development Bank (NDB). The bank, established in 2015 by the BRICS nations to “mobilize resources for infrastructure and sustainable development projects in BRICS and other emerging markets and developing countries,” remains one of the grouping’s most tangible tools.
Despite ten years of operation, the NDB has approved only 139 projects worth about US$43 billion, distributed mostly among its core members. Its counterpart, the Asian Infrastructure Investment Bank (AIIB), established around the same time, meanwhile, has gathered 111 approved members and committed some $69 billion to 350 projects, backed by a AAA credit rating that the NDB cannot easily achieve. Stagnant asset growth continues to limit its lending capacity. This is coupled with an exceptionally low payout rate; According to the bank’s own data, only about $20 billion of approved loans have been disbursed.
Breaking the asset bottleneck
One way to break this asset bottleneck would be for the five countries to increase their paid-up capital. However, severe domestic and geopolitical constraints mean that not all founders can achieve higher commitments – particularly Russia, which is heavily sanctioned. The sanctions also strained the bank’s creditworthiness and dollar cost of funding. Ironically, even as Moscow and Beijing advocate de-dollarization, including through the bank, the NDB has not extended any new credit to Russia since March 2022 to protect its AA/AA+ credit rating. And because the bank’s rules mandate equal voting shares among founders, any capital expansion is effectively held hostage to its financially weakest link. The NDB has also opened its doors to new members, allowing for a new infusion of capital, but the founders’ collective voting share cannot fall below 55%.
Regardless of how the sticking point is resolved, it makes sense to re-prioritize the NDB within BRICS. So far the bank has served Delhi well. It has secured commitments of nearly USD 10 billion across 32 projects, including metro rail systems and the Delhi-Ghaziabad-Meerut RRTS corridor. This is no small thing, but expanding the NDB’s operations to be on par with other multilateral lenders would require expanding such business to many more emerging markets and developing countries.
A notable strength of NDB is also its strong preference for local currency loans. This mechanism appeals to emerging economies, especially at a time when volatility in foreign exchange markets is maintained due to global wars, both military and economic. It is an alternative way to reduce dependence on the dollar without replacing it as a business invoicing currency. The bank’s general strategy for 2022–26 commits to 30% of its lending and borrowing in local currencies of member countries, although the majority of its borrowing and lending remains in dollars. Regardless of whether there are local currency loans, they are heavily skewed in favor of the renminbi – just a few days ago the NDB priced a three-year Panda bond at 7 billion yen (~$1.04 billion) on the Chinese interbank bond market. In 2026, issuance of these bonds increased by around 91% year-on-year, according to Chinese data.
Rupee bond printing
The time has come for India to push the long-delayed rupee bond. First mooted in 2016 and subsequently scheduled for October 2023 and then the end of March 2026, the first issue was described by NDB President Dilma Rousseff in May as being in the “final phase”, two months after the bank launched a rupee bond program to mobilize around ₹25,000 crore over five years. Since the 2026 New Delhi Declaration did not include a meaningful agreement on mobilizing NDBs, India should focus on easier fixes to its local currency problems in the next year at BRICS.
Unlike the Shanghai Cooperation Organization, whose summit recently ended with bare minimum results, BRICS has tangible economic tools and a broader membership base than ever before. In a world moving toward subscription multilateralism, the latest exemplar of which is the rules-based Washington Peace Council, these arrangements are the only way for groupings to truly differentiate themselves.
(Amit Kumar and Anushka Saxena are researchers at the Takshashila Institution. Views are personal to the authors and do not represent those of the institution. Graphic data source: NDB; Investor Presentation June 2026 & Annual Report 2025; created by authors)
Published – 14 Sep 2026 08:30 IST