Nirmala Sitharaman hopes for an India-US trade deal soon | Today’s news
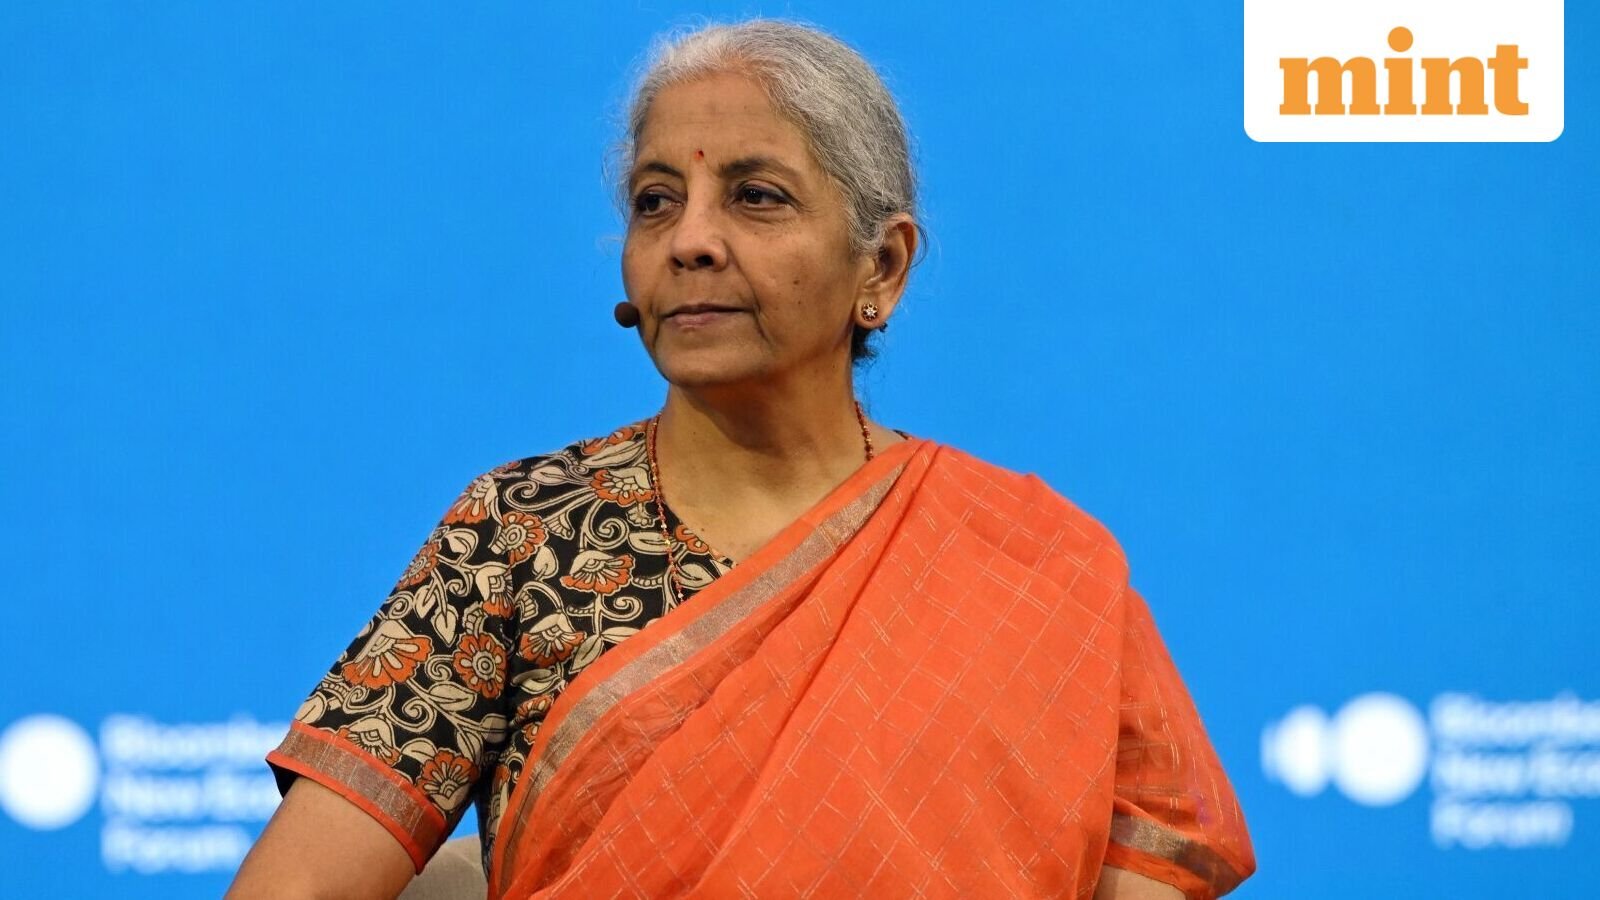
New Delhi: Union Finance Minister Nirmala Sitharaman on Friday expressed hope that the proposed India-US trade deal would be concluded at the earliest in the interest of bilateral as well as global trade.
Union Commerce and Industry Minister Piyush Goyal also wanted a mutually beneficial deal to be signed soon, she said during an interview with foreign policy expert Michael Kugelman at the US think tank Atlantic Council, on the sidelines of the annual meetings of the World Bank Group and the International Monetary Fund in Bangkok.
On Thursday, Goyal said that the first phase of the Indo-US trade agreement has been completed and is now being legally prepared. He expressed confidence that the deal would be finalized and operationalized soon, but only after India secures an export advantage over its competitors in the US market.
Read also | Sitharaman acknowledges debate on LTCG, STT but makes no budget promises
The US ambassador to India, Sergio Gore, said on Thursday that negotiations on a trade deal were progressing at an “incredible pace” and that “big things are being done”.
In February, the two countries agreed on a framework agreement that reduced punitive tariffs on most Indian goods from 50% to 18% in August 2025.
The US remained India’s largest merchandise export destination in the first half of the current fiscal year through March 2027, with shipments up 11% from a year earlier to $50.8 billion.
Read also | Nirmala Sitharaman: RBI is trying to limit the volatility of the rupee, not fix its value
While trade talks are underway, a new US law empowering President Donald Trump to impose up to 100% tariffs on countries buying Russian oil has added to India’s discomfort. New Delhi has said it will take all necessary steps to ensure energy security for the country’s 1.4 billion people.
India’s growth trajectory
Sitharaman emphasized that India has maintained its growth momentum “against all odds” and remains the world’s fastest growing major economy from 2021-22.
Both the World Bank and the IMF this month raised their FY27 growth projections for India by 50-60 basis points to 7.1% and 7%, respectively, after the country posted a stronger-than-expected 7.8% expansion in the June quarter.
“Public spending on capital expenditure has helped us build infrastructure in the country and that has a bigger multiplier effect,” she said.
She also said the government’s focus on inclusiveness and “making sure everyone has access to resources and access to skills” while adhering to fiscal prudence has helped the economy, the minister said.
Read also | Sitharaman offers Indian investment opportunities to investors in Singapore
“We are aware that we have a responsibility for public money, so we are very clear that we cannot spend money, even though we have to look after those who are vulnerable in the economy,” she said.
The central government began to sharply increase its capital spending after 2020 in order to quickly restore the economy hit by the pandemic. It maintained such spending to partially offset subdued private investment.
While private investment has picked up again, lifting gross fixed capital formation growth to a three-year high of 11% in the June quarter, public spending remains the key driver of growth as the war in West Asia has raised new uncertainties.
The center has budgeted its capital expenditure for FY27 at ₹12.22 trillion, a sharp increase ₹3.36 trillion in FY20. Its effective capital expenditure, after accounting for subsidies to states for capital asset formation, is budgeted to exceed ₹17 trillion in FY27, about 32% of the total budget.
“So when you spend public money to build infrastructure, the multiplier that creates is different from what it would be if you put that money directly into people’s hands,” she said.
“So in that way, I think the multiplier has really worked and it’s worked out very well for us in these tough times,” the minister added.
Reforms in multilateral bodies
Sitharaman called on multilateral organizations such as the World Bank and the IMF to be “more responsive”, reiterating that they “have to meet the expectations of the 21st century because they are Bretton Woods institutions”.
“Countries that were in the middle-income group suddenly find themselves in desperate balance-of-payments struggles and need IMF help,” she said. “An answer can’t come years later. They’re desperate for help and there’s no solution for almost three or four years,” she said, adding that “these things are now being fixed”.
In addition, new issues have emerged, such as those related to cross-border and technology-driven payments, stablecoins or central bank-driven currencies that require swift action, she suggested.
Countries including Sri Lanka, Argentina, Egypt, Ghana and Zambia have faced crises in recent years due to the deterioration of their external balances.